Independent Medicare advisors in Tucson since 2011
Medicare, explained kindly and chosen with care
Licensed local advisors line up the plans we offer against your doctors, your prescriptions and your budget. No cost to you, and no call centre.
- 4.9 from 1,137 reviews
- 11 insurance companies compared
- TTY 711
 Tucson, Oro Valley and Green Valley
 One advisor, every year
 English y español
- Licensed by the Arizona Department of Insurance
- Independent: 11 insurance companies, 64 products
- AHIP certified every year, all advisors
- No fee to you, ever
- TTY 711 and bilingual advisors
Start with the part that is on your mind
Medicare arrives in pieces, and almost nobody needs all of them explained at once. Pick the piece you are stuck on and we will show how it fits with the rest.
 Most chosen in Pima CountyMedicare AdvantagePrivate plans approved by Medicare that bundle hospital, medical and usually drug coverage, often with dental and vision.Explore Advantage plans
 Original MedicareParts A and B: the federal foundation everything else sits on.Medicare SupplementMedigap pays the 20% that Part B leaves behind.Part D drug plansPriced against your exact prescriptions and pharmacy.Special Needs PlansFor AHCCCS members and chronic conditions.
 Dental, vision and hearingCleanings, glasses, hearing aids and OTC allowances.Drug costs too high?Extra Help, the payment plan and a full formulary review.Get prescription helpHablamos españolRosa y Tomás explican Medicare con calma, en su idioma.
Plan G, Plan N or High-Deductible G
Every insurance company sells the same lettered Medigap benefits, so the letter decides what is covered and the company only decides the price and the service. These are the three letters Southern Arizonans actually choose between.
Premiums shown are sample ranges for a 65-year-old non-smoker in Tucson ZIP 85711 and are for illustration only.
| Benefit | Plan GThe most chosen letter in Pima County | Plan NLower premium, small copays at the desk | High-Deductible GLowest premium, you self-insure first |
|---|---|---|---|
| Part A hospital deductible$1,736 per benefit period in 2026 (sample) | Paid in full | Paid in full | Paid after your $2,980 deductible |
| Part B coinsurance (the 20%)Doctor visits, imaging, outpatient surgery | Paid in full | Paid, minus up to $20 per office visit and $50 per ER visit | Paid after your deductible |
| Part B deductible$283 a year. No letter sold after 2020 may cover it | You pay it | You pay it | You pay it, and it counts toward the $2,980 |
| Part B excess chargesUp to 15% above the Medicare rate from doctors who do not accept assignment | Paid in full | You pay them | Paid after your deductible |
| Skilled nursing coinsuranceDays 21 to 100 of a covered rehab stay | Paid in full | Paid in full | Paid after your deductible |
| Foreign travel emergency80% of billed charges, $50,000 lifetime cap | Included | Included | Included after your deductible |
| Extra 365 hospital daysAfter Original Medicare days run out | Included | Included | Included |
| Yearly deductible you pay first | None | None | $2,980 a year |
| Sample monthly premium | $148 to $182 a month | $112 to $138 a month | $38 to $56 a month |
Plan G
The most chosen letter in Pima County
- Sample premium
- $148 to $182 a month
- Yearly deductible
- None
- Part A hospital deductible
- Paid in full
- Part B coinsurance (the 20%)
- Paid in full
- Part B deductible
- You pay it
- Part B excess charges
- Paid in full
- Skilled nursing coinsurance
- Paid in full
- Foreign travel emergency
- Included
- Extra 365 hospital days
- Included
Plan N
Lower premium, small copays at the desk
- Sample premium
- $112 to $138 a month
- Yearly deductible
- None
- Part A hospital deductible
- Paid in full
- Part B coinsurance (the 20%)
- Paid, minus up to $20 per office visit and $50 per ER visit
- Part B deductible
- You pay it
- Part B excess charges
- You pay them
- Skilled nursing coinsurance
- Paid in full
- Foreign travel emergency
- Included
- Extra 365 hospital days
- Included
High-Deductible G
Lowest premium, you self-insure first
- Sample premium
- $38 to $56 a month
- Yearly deductible
- $2,980 a year
- Part A hospital deductible
- Paid after your $2,980 deductible
- Part B coinsurance (the 20%)
- Paid after your deductible
- Part B deductible
- You pay it, and it counts toward the $2,980
- Part B excess charges
- Paid after your deductible
- Skilled nursing coinsurance
- Paid after your deductible
- Foreign travel emergency
- Included after your deductible
- Extra 365 hospital days
- Included
The trade-off in one line: Plan G buys the fewest surprises, Plan N trades small copays for a lower premium, and High-Deductible G is the cheapest premium if you can comfortably absorb the first $2,980 in a bad year.
"Nobody should have to decode a 200-page Evidence of Coverage on their own kitchen table. That is the whole job. We read it, and then we explain it in the words you actually use."
The Part B late penalty is permanent. Here is the arithmetic
Miss your window without creditable employer coverage and Social Security adds 10% to your Part B premium for every full 12-month period you went without it. The surcharge does not expire when you finally enroll. It follows you for as long as you have Part B.
- Only full 12-month periods count, so 14 months late costs the same as 12 months late.
- Group coverage from an employer with 20 or more employees usually protects you. COBRA, retiree plans and marketplace coverage do not.
- If you were misinformed by an employer or a federal employee, you can ask Social Security for equitable relief.
Work out the surcharge
Months are counted from the end of your Initial Enrollment Period, or from the end of employer coverage.
- Full 12-month periods counted
- 0
- Penalty rate added
- 0%
- Standard Part B premium
- $214.60
Based on a sample 2027 standard premium of $214.60. Your own premium may be higher if IRMAA applies. Part D has a separate, smaller penalty of 1% of the national base premium for each month without creditable drug coverage.
Check my timing with an advisorDrag the handle: one neighbour, one October review
Ray and Delia in Midvale Park had not changed plans since 2019. Their doctors stayed the same, their prescriptions stayed the same, and their costs still fell. Slide across to see what an hour at the kitchen table moved.
- Monthly premium$168$0Moved from a Medigap plan they had outgrown to an Advantage plan that keeps their cardiologist
- Insulin, per month$84$35Covered insulin is capped at $35 on every Part D and Advantage plan
- Yearly drug total$1,940$1,328Same drugs, different formulary tier and a preferred pharmacy on Speedway
- DentalNot covered2 cleaningsPlus a $1,500 yearly allowance for fillings and crowns
Composite example with sample figures. Savings depend on your own drugs, doctors and ZIP code.
 BeforeAfter
IRMAA, and the tax return you filed two years ago
Most people pay the standard Part B premium. Higher earners pay an income-related monthly adjustment amount on top of both Part B and Part D, and Social Security decides it from the modified adjusted gross income on your return from two years earlier. A 2027 premium is set by your 2025 return. That surprises nearly every client who retired last year.
| 2025 income, filing single | 2025 income, married filing jointly | Part B each month | Part D surcharge |
|---|---|---|---|
| $109,000 or less | $218,000 or less | $214.60 | No surcharge |
| Over $109,000 up to $137,000 | Over $218,000 up to $274,000 | $300.40 | +$14.50 |
| Over $137,000 up to $171,000 | Over $274,000 up to $342,000 | $429.20 | +$37.50 |
| Over $171,000 up to $205,000 | Over $342,000 up to $410,000 | $558.00 | +$60.40 |
| Over $205,000 up to $500,000 | Over $410,000 up to $750,000 | $686.70 | +$83.30 |
| $500,000 or more | $750,000 or more | $729.60 | +$91.00 |
The cliff is a hard edge, not a slope
One dollar over a bracket moves you into the whole bracket. A Roth conversion, a capital gain on a Tucson rental, or a large required minimum distribution can cost a couple several thousand dollars in Medicare premiums two years later. We look at the return before you file, not after.
IRMAA is recalculated every year, so a single high-income year affects a single year of premiums once the lookback has passed.
If the income has already stopped, appeal it
Form SSA-44 asks Social Security to use your current income instead of the two-year-old return, if one of these life-changing events applies.
- You retired or cut your hoursWork stoppage and work reduction are both accepted life-changing events.
- Marriage, divorce or widowhoodA change in filing status moves you to a different column of the table.
- Loss of income-producing propertyA sale forced by disaster or fraud counts. A voluntary sale does not.
- Loss of a pension or a settlementAn employer pension that stopped, or an employer settlement payment.
We fill out SSA-44 with clients at the Broadway office and walk the form to the Tucson Social Security field office. There is no charge for that.
Three offices, and a kitchen table anywhere in between
Come to us, or we will come to you. Home visits across Pima and Cochise counties are part of the service, not an upsell.
All service areas
Tucson
Our main office on East Broadway, with in-person appointments six days a week during enrollment season.
4400 E Broadway Blvd, Suite 210, Tucson, AZ 85711
Today: 8:00 am to 6:00 pm
Green Valley
A satellite office near the recreation centers, open Tuesdays and Thursdays.
101 S La Cañada Dr, Suite 14, Green Valley, AZ 85614
Today: 8:00 am to 6:00 pm
The advisor you meet is the advisor you keep
Six licensed people, all of them local. You will have a direct line to yours, and the same one calls you every October.
More about Sagebrook Rosa VillanuevaFounder and senior advisor
Licensed since 2009. Started Sagebrook after helping her own parents through Medicare in Nogales.
English, Español Mei Lin HarperPart D and pharmacy specialist
A former pharmacy technician who reads formularies for fun and finds savings most people miss.
English, Mandarin Danielle OkaforClient care manager
Keeps every follow-up on schedule and helps clients with claims, ID cards and billing questions.
English Marcus BellMedigap and retirement advisor
Spent 14 years in employee benefits and now helps people leave employer plans on the right date.
English Tomás AguirreBilingual advisor, Green Valley
Runs our Green Valley office and our Spanish-language seminars at the Joyner-Green Valley Library.
English, Español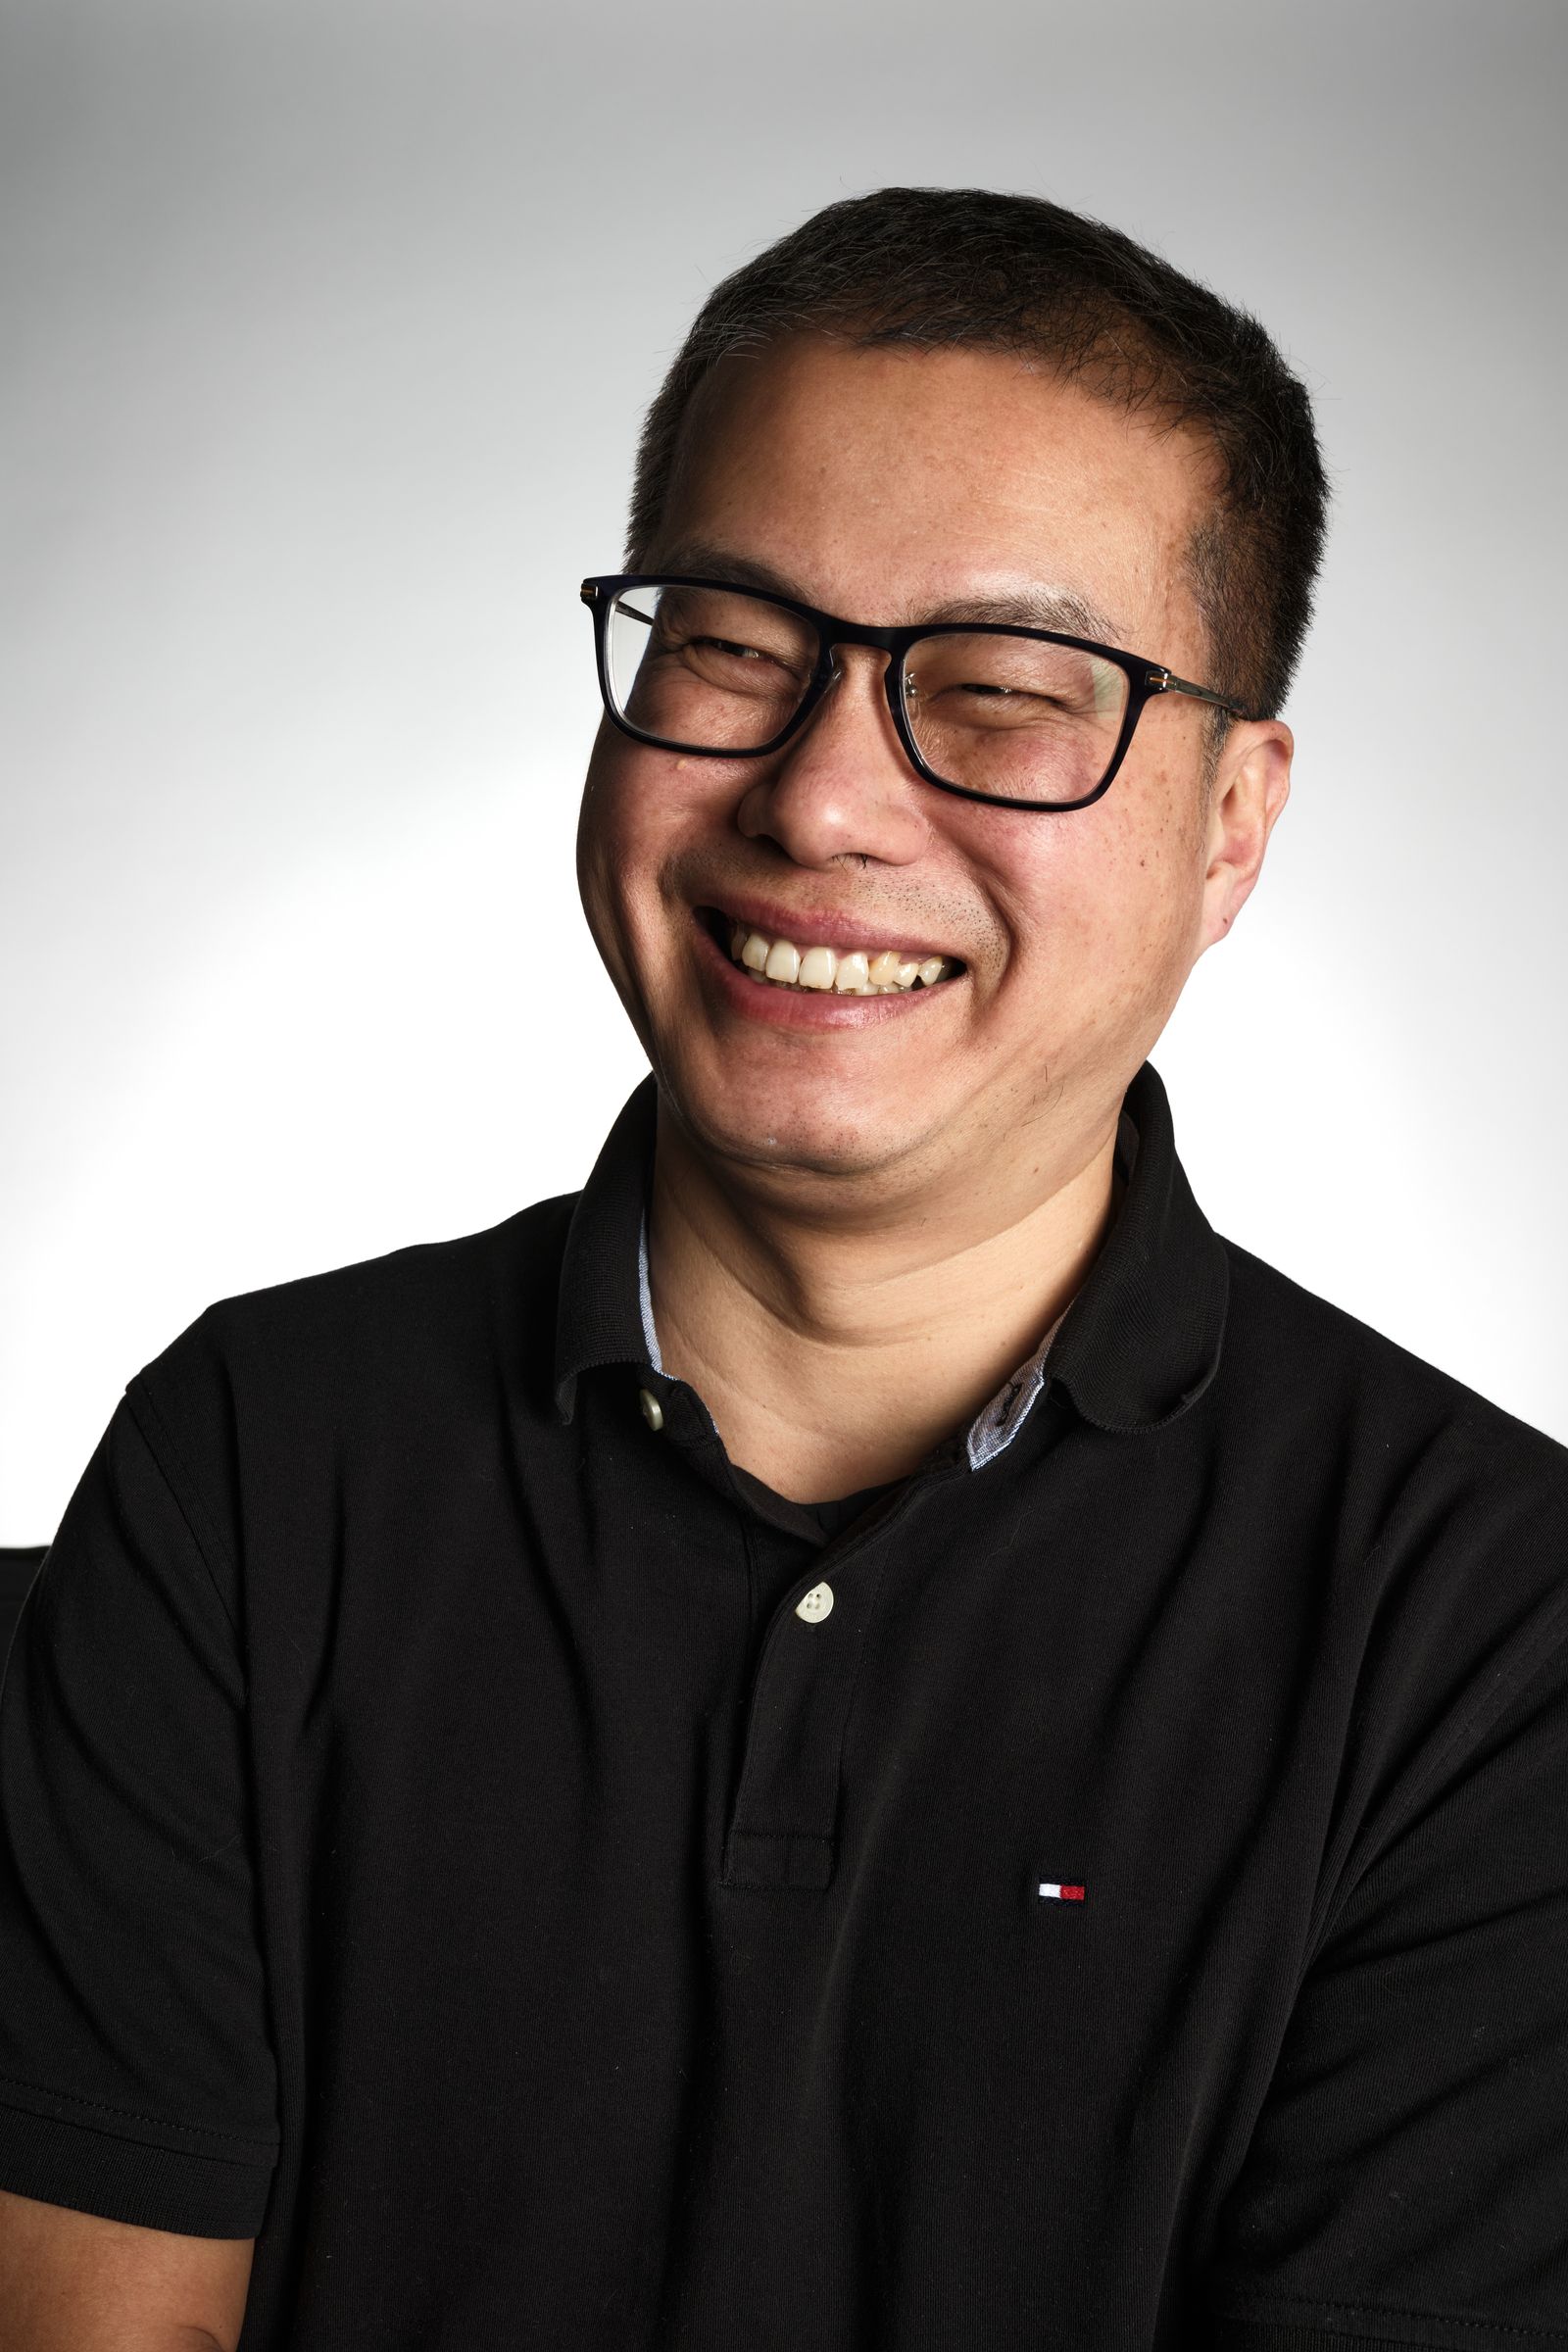 Walt BrennanVeterans and TRICARE advisor
Retired Army, 22 years. Helps Fort Huachuca families coordinate Medicare, VA and TRICARE for Life.
English
4.9
1,137 neighbours have been through this with us
Verified reviews from clients across Pima and Cochise counties.
Read all reviewsRosa explained Parts A and B at my kitchen table with a pot of coffee. I finally understood my enrollment dates and signed up with no penalty.
Marcus compared five Plan G companies and showed me their rate history. I am paying $31 less a month than my old quote.
Tomás me explicó todo en español, con paciencia. Mi mamá y yo salimos con un plan que cubre a su doctor de siempre.
We moved from Ohio and had no idea which plans worked with local doctors. Sagebrook checked every one before we enrolled.
Mei Lin ran my eight prescriptions through every plan. My yearly drug cost dropped by about $1,400.
What a year with Sagebrook looks like
Seminars, kitchen tables, pharmacy counters and a lot of coffee.
So here is exactly how it goes
Four steps, no pressure at any of them, and the same advisor every year. Most people are done in a single conversation.
Tell us what matters
Your doctors, prescriptions, budget and travel plans. By phone, video or at your table.
Compare side by side
We line up the plans we offer in your ZIP and show real yearly costs.
Choose and enroll
You decide, with no pressure. We handle the application and confirm your card arrives.
Review every fall
Each October we re-check your plan so changes never catch you off guard.
An advisor picks up the phone, not a call centre. TTY 711. English y español, every day we are open.